
- Installs
- —
- Apple does not publish download counts
- Rating
- —
- Ratings
- —
- Version
- 19.5
- Updated 6 Apr 2026
- Released
- 15 Jan 2020
- Tracked since 10 May 2026
- Size
- 2 MB
- Needs 10.15
Screenshots


About MCarloRisk3D
The description on the store listing
Monte Carlo forecaster from raw asset price data including crypto, with extensive backtesting and tuning.
Now including portfolio features...available in a separate sub-window of this app!
- construct portfolios of stocks, ETFs, and popular crypto assets
- examine historical returns distributions for one asset at a time, with distribution metrics computed automatically such as mean return, volatility, skew (bullish/bearish), kurtosis (fat tail metric), and tail ratio (fat tail bias: bullish or bearish)
- generate monte carlo forecast models for a full portfolio, accounting for for inter-portfolio historical return correlations
- backtest these models, either in single pass batch mode or …
Read the full description
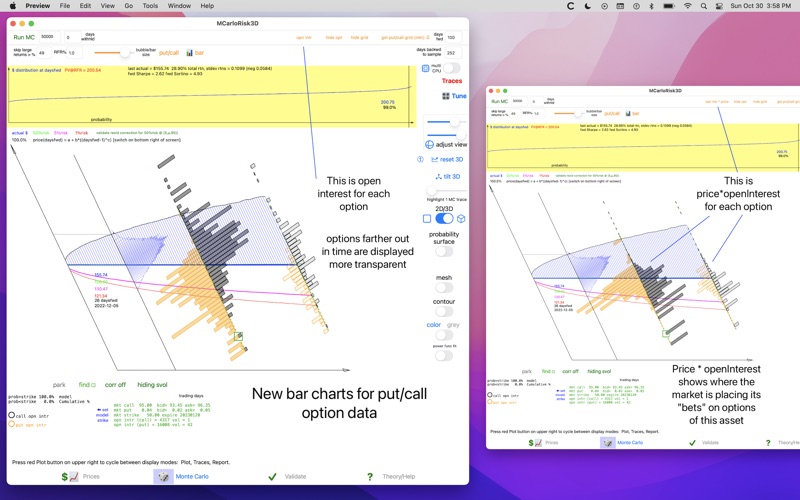
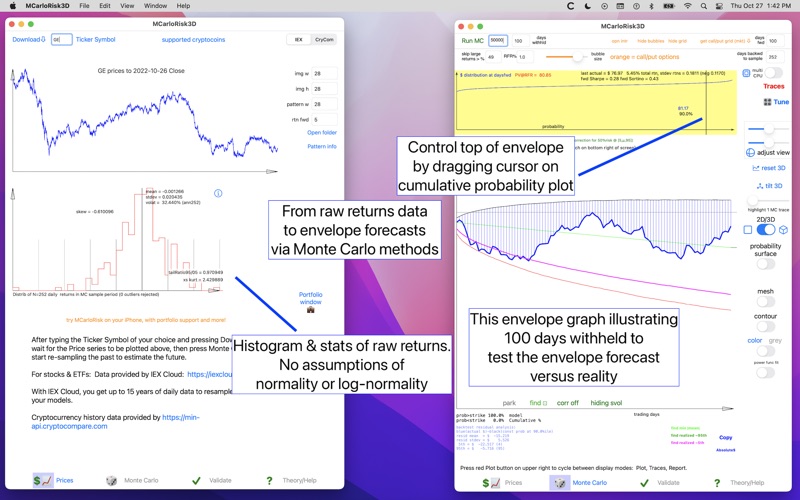
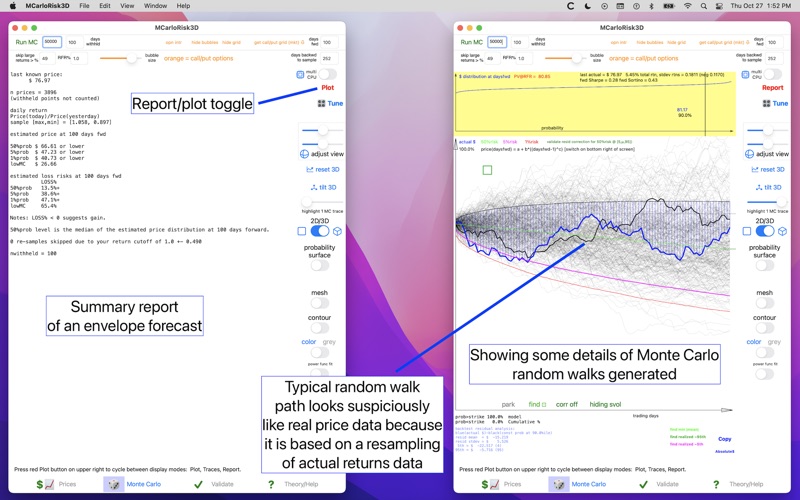
Monte Carlo forecaster from raw asset price data including crypto, with extensive backtesting and tuning. Now including portfolio features...available in a separate sub-window of this app! - construct portfolios of stocks, ETFs, and popular crypto assets - examine historical returns distributions for one asset at a time, with distribution metrics computed automatically such as mean return, volatility, skew (bullish/bearish), kurtosis (fat tail metric), and tail ratio (fat tail bias: bullish or bearish) - generate monte carlo forecast models for a full portfolio, accounting for for inter-portfolio historical return correlations - backtest these models, either in single pass batch mode or exhaustive backward-stepwise validation - tune models to backtests using a variety of tuning parameters, including sample window size adjustment, adding black swan events of various magnitude and probability, and accounting for longer term memory in historical data - choose strike price and estimate over/under probability at various future times (of portfolio or individual assets) - use multi core CPUs for faster validation - get simple metric reports and detailed graphs of validation results - example pairwise correlation of historical returns in your portfolio - optimize a portfolio for various targets, with user settable weights on probability-based targets - construct multiple regression models (alpha / multi-beta) on regular assets or ETFs which stand in as surrogates for the full market (SPY) or sub-sectors (e.g. tech sector, low cap stocks, high cap stocks, growth, value, etc) - compute novel beta metrics such as "beta to Bitcoin" - backtest your beta models to check for robustness, and plot beta stability Resamples from empirical daily returns to generate forward-in-time monte carlo paths (random walks), with user-adjustable long memory modifications such as the Hurst exponent, serial resampling, and fractional differencing. No distribution shape assumptions needed, works with empirical returns distribution. This is especially useful for new assets such as crypto or more exotic equities such as TSLA that may not conform to normal or lognormal return assumptions, especially in shorter time periods. Brownian motion becomes Empirical motion in this app, since we use an empirical distribution. Similarly, fractional Brownian motion becomes fractional Empirical motion in this app, for one of the long memory options. Aggregates monte carlo paths into a (price, time, probability) surface. Allows user to move sliders to slice thru and examine this surface (e.g. price over time versus probability) and visualize the surface in 3D and with shaded contour plots. Allows user to set up bulk backtests or exhaustive backtests to validate model. Quick summary metrics of exhaustive backtests are computed to estimate model quality. Many model tuning parameters to adjust model to observed backtests: - add black swan events (symmetric or non symmetric) - tune skew and volatility of historical empirical distribution - add long memory capability to the monte carlo paths (as noted above) Set strike price to slice thru probability surface along time axis to estimate probability over/under strike at a given time forward, or cumulatively up to a given time. Estimate put/call prices using the model you build and verify (not limited to market expiry or strike). Compare modeled put/call prices w/ market put/call prices at published market expiry dates and strikes. Bubble grid plot of market put/call open interest, open interest * price, and raw put/call price at all published market expiry dates and strike prices (IEX Cloud-supplied data): to visualize where investors are putting their money on the options grid. Compare market option prices at a grid point to your modeled prices. Detailed training and examples available online in Help tab. Raw price data from IEX Exchange or cryptocompare.com
Installs
Apple does not publish download counts. Estimates are in testing.
We publish iOS estimates only after they pass a back-test against real numbers. Chart history below is measured.
Estimated store revenue Estimated Beta
App Store, worldwide, monthly rate from the last 14 chart days to 21 Nov 2026
Below the top 100 grossing apps in the markets we calibrate. In the United States that usually means under about $6.4M a month. App Store purchases and subscriptions only, before Apple's 15 to 30% fee. Ads and web payments are not included.
Ratings
No rating breakdown published for this app.
Recent reviews
Latest public reviews from the store
No reviews in our sample for this app yet.
Top chart positions
Latest App Store chart ranks by country, last 10 days
Not in any tracked top chart in the last 10 days.
MCarloRisk3D history
Release, install milestones, listing and store changes
- First released on the store 15 Jan 2020
Update frequency
How often MCarloRisk3D ships a new version, month by month
1 updates in the last 12 months. Less often than most similar apps: they shipped a median of 2 updates in the same year.
Recent versions
Current version 19.5
- Version 19.56 Apr 2026
Update to newer Xcode. This causes the tab bar to move to the top of the app without icons due to new Apple UI standards, with a 'segmented control' or 'pulldown menu' look. Fix issues related to this update. Add link to our new OptiViz app.
Listing keywords
Words and phrases MCarloRisk3D repeats most in its store listing
Top phrases: monte carlo (5), put call (5), monte carlo paths (3), put call prices (3), call prices (3).
Highlighted words also appear in the title. Counts cover the title, short description and description.
Compliance
What the listing and the app package show
- Store status
- Live
- Upkeep
- Updated 6 Apr 2026
- Age rating
- 4+
Apps like MCarloRisk3D
 BofA Point of Sale - MobileBank of America★ 3.88
 Purpl Digital WalletPurpl SAL★ 4.54
 Expedier: Send Money GloballyEXPEDIER INC★ 4.52
 Cenoa: Get Paid GloballyCENOA PTE. LTD.★ 4.62
 Texas Traditions MobileTexas Traditions Bank★ 4.74
 Minhas Finanças | PessoaisNimtech Tecnologia da Informacao LTDA★ 4.94
 SkyCashSkyCash★ 2.78
 FactSet 2.0 (legacy)FactSet Research Systems, Inc.★ 3.96
 My Funds - Portfolio TrackerQTech Solutions Pty Ltd★ 3.78
MCarloRisk3D: questions and answers
Who makes MCarloRisk3D?
MCarloRisk3D is published by differential enterprises.
When was MCarloRisk3D last updated?
The latest version (19.5) was released on 6 Apr 2026.
Is MCarloRisk3D free?
Yes. MCarloRisk3D is free to download.
Is MCarloRisk3D still available?
Yes. MCarloRisk3D is live on App Store as of 10 May 2026.
Track MCarloRisk3D and its competitors
Watch any app for new versions, rating drops, chart moves and removals. Free plan, no card.